
Seven contract clauses small businesses should check before signing a service agreement
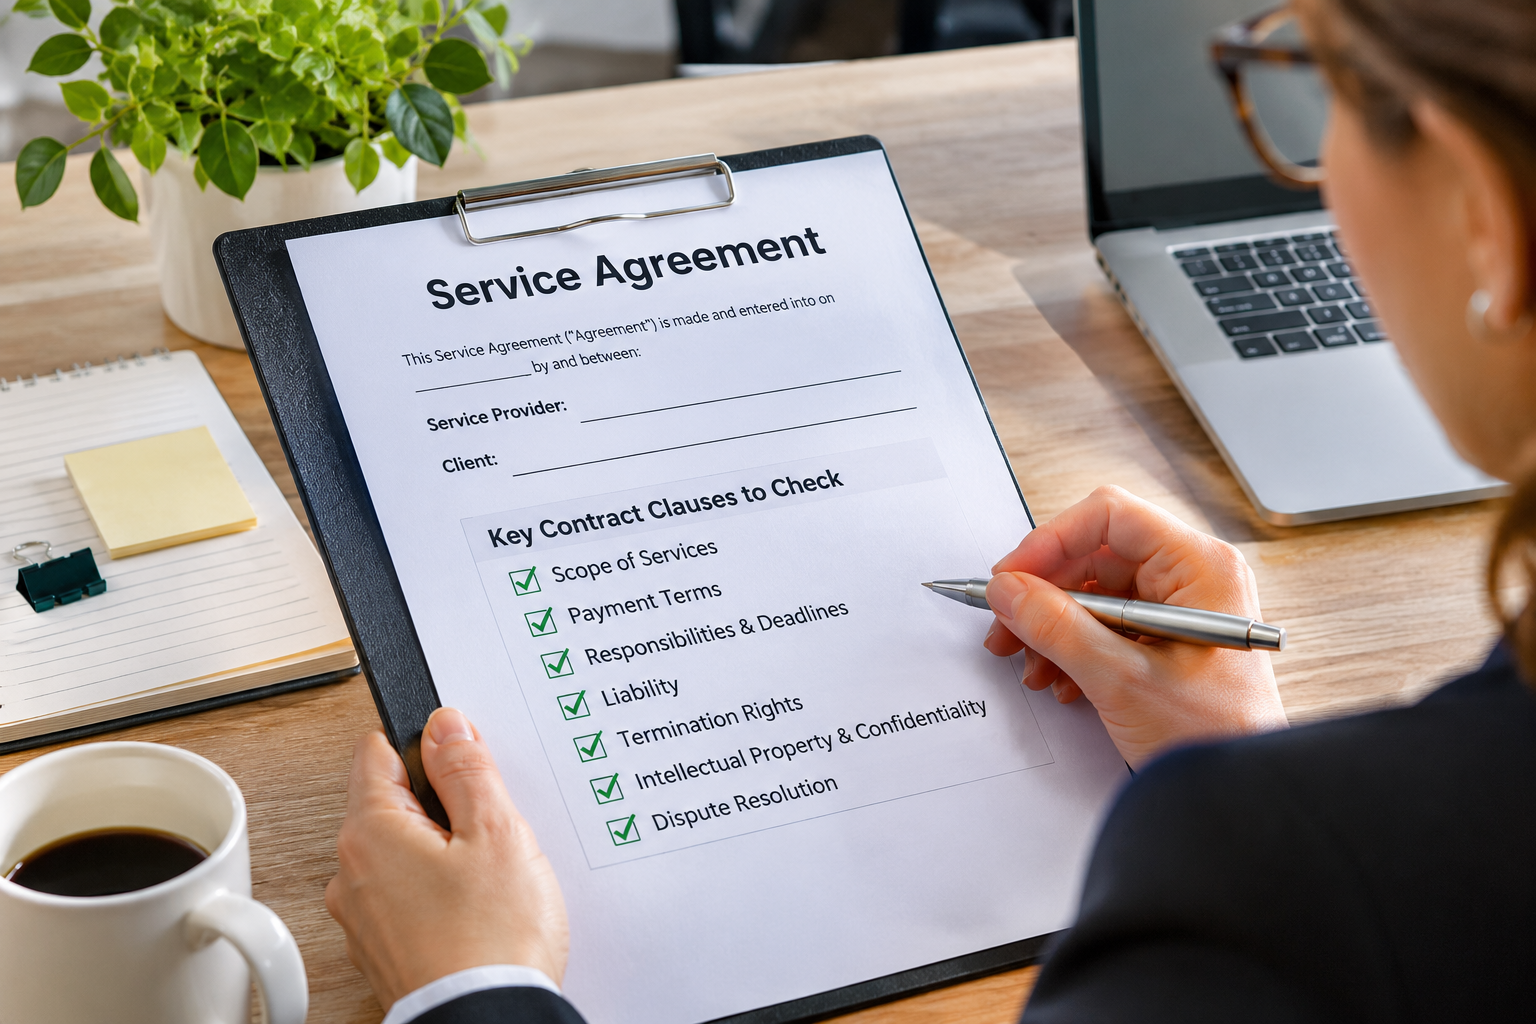
Before signing a service agreement, every small business should check 7 essential contract clauses: scope of services, payment terms, responsibilities and deadlines, liability, termination rights, intellectual property and confidentiality, and dispute resolution. These clauses determine what you are paying for, what happens when something goes wrong and how easily you can end the arrangement. Unclear wording can leave you paying unexpected fees, accepting unnecessary risks or struggling to recover money owed to your business.
Whether you run a consultancy, marketing agency, cleaning company, construction business or another service-based organisation, the same basic principle applies. A service agreement should protect both parties by making their obligations clear.
The problem is that many agreements look straightforward until you examine the details. A contract might describe the work accurately but say very little about additional charges. Another might specify a monthly price while allowing the supplier to increase it with limited notice.
You do not need to understand every legal expression to recognise these risks. However, you should know which service agreement clauses UK businesses need to examine before committing.
What is a service agreement, and why does your business need one?
A service agreement is a legally binding contract that explains the services one party will provide to another, the price payable and the responsibilities of each party. It should also establish what happens if work is delayed, payments are missed, the service is unsatisfactory or either party wants to end the arrangement.
For small businesses, a properly drafted agreement provides greater certainty over costs, delivery and expectations.
For example, imagine you hire a marketing agency for £1,500 per month. You expect the agency to manage your advertising campaigns, produce monthly reports and attend regular review meetings.
The agency believes its obligation is limited to campaign management, with reporting and meetings charged separately.
Both parties may believe their interpretation is reasonable. Without a clearly defined scope of services, that disagreement can become expensive.
A written agreement helps establish what was actually agreed, rather than relying on conversations or assumptions.
It also provides useful evidence if a contractual dispute arises.
The 7 essential service agreement clauses UK small businesses should review
Not every business contract needs the same wording. A 1-month consultancy project will have different requirements from a 3-year outsourced services agreement.
Nevertheless, the following 7 clauses deserve careful attention before you sign.
1. Scope of services: make sure you know exactly what is included
The scope of services clause should explain precisely what the supplier will deliver, what is excluded and how completion or satisfactory performance will be assessed.
A vague description such as "providing ongoing business support" leaves considerable room for disagreement.
Instead, the agreement should identify the work being undertaken, expected deliverables, relevant standards and any limitations.
What should a scope of services clause include?
Depending on the nature of the project, check whether the contract identifies:
Specific Deliverables: The products, documents, services or outcomes you should receive.
Service Frequency: How often the supplier must complete particular activities.
Performance Standards: The quality or measurable standards the supplier is expected to meet.
Excluded Services: Work that falls outside the agreed price.
Additional Work: How changes to the original scope will be requested, approved and charged.
Acceptance Criteria: How completed work will be reviewed and accepted.
A website development agreement, for example, should ideally explain how many pages are included, whether the supplier will create the content and how many rounds of revisions are permitted.
If those details are absent, an apparently fixed-price project can become considerably more expensive.
Watch out for vague wording
Pay particular attention to expressions such as "reasonable support", "as required" or "additional services may incur charges".
These phrases are not necessarily inappropriate, but their meaning should be clear in the context of the agreement.
If a supplier can decide unilaterally whether something constitutes additional work, consider asking for a written approval process.
A practical approach: Require written confirmation of any change to the agreed scope, including its cost and effect on the delivery schedule, before additional work begins.
2. Payment terms: understand when, how and why you will be charged
Payment clauses should identify the agreed price, invoicing arrangements, payment deadlines and consequences of late payment. They should also explain whether deposits, expenses, additional work or price increases can be charged separately.
For smaller businesses, this clause is particularly important because unexpected payment obligations can affect cash flow even when the underlying service is satisfactory.
Check when payment becomes due
A service agreement may require payment:
In Advance: Before the supplier begins providing services.
On Completion: Once the agreed work has been delivered.
At Agreed Milestones: After specific stages of the project have been completed.
At Regular Intervals: Monthly, quarterly or according to another agreed schedule.
None of these arrangements is automatically unsuitable.
What matters is whether the payment structure reflects the work being performed and the financial risk you are accepting.
For example, paying 100% upfront for a substantial project may expose your business if the supplier fails to deliver.
A staged payment arrangement linked to clearly defined milestones may provide more protection.
What are the rules on late payment in UK business contracts?
Under the Late Payment of Commercial Debts (Interest) Act 1998, qualifying business-to-business debts can attract statutory interest when payment is overdue.
The statutory rate is 8% plus the Bank of England base rate, subject to the applicable rules and contractual provisions.
The Government's guidance explains that business payment periods should generally not exceed 60 days, although longer periods can be agreed where they are fair to both businesses.
If the parties have not agreed a payment date, statutory rules determine when payment becomes late, generally by reference to a 30-day period.
You can review the current requirements through the GOV.UK guidance on late commercial payments.
GOV.UK+1
You should also check whether the agreement contains a contractual late-payment interest rate. A contractual provision can affect whether statutory interest is available, and the legislation contains safeguards against inadequate contractual remedies.
Example: how an unclear payment clause causes problems
Suppose you provide maintenance services to another company for £2,000 per month.
Your agreement states that invoices are payable "following satisfactory completion of services".
The customer subsequently refuses to pay because it believes certain maintenance tasks remain outstanding.
Without a clear definition of satisfactory completion, the dispute may become difficult to resolve.
A better agreement would identify the services required, how completion is recorded, when invoices become payable and how genuine disputes over invoiced amounts should be handled.
If your business is already dealing with unpaid invoices, paralegal debt recovery assistance may help you prepare appropriate correspondence and organise supporting documents.
3. Responsibilities and deadlines: establish who must do what
A responsibilities clause explains what each party must contribute to ensure the services can be delivered. It should also address deadlines, dependencies and what happens when delays occur.
This matters because suppliers and customers often have responsibilities that depend on each other.
If one party fails to provide information, access or approvals on time, the other may be unable to perform its obligations.
Define responsibilities for both parties
Consider an accounting business that engages an external IT provider to migrate company data to a new system.
The provider may need to complete the migration by an agreed date.
However, the accounting business may first need to provide access credentials, authorise the transfer and identify which information must be retained.
The agreement should explain what happens if these prerequisites are not completed on time.
Otherwise, each party may blame the other for the delay.
Distinguish important deadlines from estimates
Some agreements describe delivery dates as estimates rather than binding commitments.
That may be reasonable where delivery depends on factors outside the supplier's control.
However, if a specific date is commercially important, the agreement should explain its significance.
You should consider:
Project Start Date: When the supplier is expected to begin.
Completion Deadline: When the final service or deliverable must be provided.
Customer Dependencies: Information, access or approvals you must supply.
Delay Notification: When either party must report a likely delay.
Extension Arrangements: Circumstances allowing deadlines to be changed.
Failure To Deliver: What remedies are available if important obligations are not met.
A clause describing deadlines as purely indicative may offer less certainty than you expect.
You should also check whether the supplier has promised reasonable care and skill in delivering the services.
For many business-to-business service contracts in England and Wales, section 13 of the Supply of Goods and Services Act 1982 implies an obligation to exercise reasonable care and skill.
The precise application depends on the contract and circumstances.
4. Limitation of liability: know what happens if something goes wrong
A limitation of liability clause determines how much financial responsibility a party may face if it breaches the agreement or causes certain losses.
These clauses can be particularly important where a service failure could interrupt business operations, expose confidential information or result in substantial financial loss.
You should examine both the amount of liability and the types of losses the agreement excludes.
What is a liability cap?
A liability cap places a contractual limit on the amount one party may be required to pay for certain claims.
For example, an agreement worth £12,000 annually might limit the supplier's total liability to the fees paid during the preceding 12 months.
That arrangement may be commercially acceptable in some situations.
However, imagine the service concerns an essential business system and a serious failure could cause losses far exceeding the annual contract value.
You would need to consider whether the proposed limitation provides an appropriate allocation of risk.
The fact that a liability cap appears in a contract does not automatically mean it is enforceable in every circumstance.
Can UK service contracts exclude all liability?
No. Contractual exclusions and limitations are subject to legal restrictions.
Under the Unfair Contract Terms Act 1977, a business cannot exclude or restrict liability for death or personal injury resulting from negligence. Other exclusions may be subject to a statutory reasonableness test.
Certain contractual limitations may therefore be ineffective, even if both parties have signed the agreement.
You can read the relevant provisions in the Unfair Contract Terms Act 1977.
Clauses that deserve particular attention
Check whether the agreement:
Caps Financial Liability: Limits compensation to a specific amount or calculation.
Excludes Lost Profits: Restricts claims for particular financial consequences.
Excludes Indirect Losses: Uses wording that may require careful legal interpretation.
Contains Indemnities: Requires you to compensate the other party for specified losses or claims.
Addresses Data Breaches: Allocates responsibility for relevant information security failures.
Provides Insurance Requirements: Specifies whether professional indemnity or other insurance must be maintained.
It is worth checking whether the restrictions apply equally to both parties.
A contract that heavily limits the supplier's liability while leaving your business exposed to broader obligations may deserve closer examination.
5. Termination clauses: understand how you can leave the agreement
A termination clause explains when and how either party can end the contract. It should identify notice periods, early termination charges, circumstances allowing immediate termination and the obligations that continue after the agreement ends.
This is particularly important for contracts involving recurring payments or automatic renewal.
Without clear termination rights, you could remain committed to a service you no longer require.
Check the difference between termination and contract expiry
An agreement may end naturally when a fixed term expires.
Alternatively, it may renew automatically unless either party gives notice.
For example, you might sign a 12-month service contract that automatically renews for another 12 months unless you provide written notice at least 90 days before the original term ends.
If you overlook that deadline, you may find yourself committed to another contractual period.
Whether the renewal provision is enforceable depends on the relevant law and circumstances, but it is better to identify the issue before signing.
What should a fair termination clause address?
A useful termination provision should explain:
Termination For Convenience: Whether you can end the agreement without alleging a breach.
Required Notice: How much notice must be provided and by which method.
Termination For Breach: Whether serious contractual failures allow the agreement to end.
Opportunity To Remedy: Whether a party must be given time to correct a breach.
Early Termination Charges: Any fees payable for leaving before the agreed end date.
Outstanding Payments: How completed work and unpaid invoices are handled.
Return Of Materials: What happens to business information, documents and equipment.
Pay close attention to contracts that allow a supplier to terminate quickly but require you to provide lengthy notice.
Do not overlook the handover process
Termination is not simply about stopping payments.
If you rely on a service provider for business-critical activities, you may need access to information, systems or documents after the relationship ends.
For example, a business changing its outsourced IT provider may need the outgoing supplier to return credentials, provide documentation and assist with the transition.
If the contract does not address these obligations, leaving the agreement may become more complicated than expected.
6. Intellectual property and confidentiality: protect your information and business assets
Intellectual property clauses establish who owns or can use work created during the service relationship. Confidentiality provisions address how commercially sensitive information must be protected.
Both are important where a supplier creates documents, designs, software, marketing materials or other valuable business assets.
You should not assume that paying for a service automatically transfers ownership of everything produced.
Who owns work created by an external contractor?
In the UK, a freelancer or independent contractor will usually retain copyright in work they create unless ownership is transferred through an appropriate written agreement.
This differs from the general position for work created by employees in the course of employment.
The UK Intellectual Property Office explains that the creator of commissioned copyright material is normally the first copyright owner unless the parties agree otherwise in writing.
See the official GOV.UK guidance on copyright ownership.
Consider a small company that pays a freelance designer £3,000 to produce a new logo and brand materials.
The business may assume it owns the finished designs outright.
However, if the contract does not properly address intellectual property ownership, the designer may retain copyright, leaving the business with rights that depend on the applicable agreement and circumstances.
An appropriate contract should clarify whether intellectual property is assigned, licensed or retained by the creator.
Check how confidential information will be handled
A confidentiality clause should define the information that must remain private and explain the circumstances in which disclosure is permitted.
It may cover:
Customer Information: Client records, contact details and commercial information.
Financial Information: Pricing arrangements, budgets and business forecasts.
Business Processes: Internal procedures, methods and operational documentation.
Intellectual Property: Designs, technical information and confidential developments.
Permitted Disclosures: Circumstances where information can lawfully be shared.
Post-Contract Obligations: Confidentiality duties that continue after the agreement ends.
You should also consider whether confidentiality obligations apply to subcontractors.
What if the supplier processes personal data?
Confidentiality clauses alone may not satisfy your data protection obligations.
If a supplier processes personal data on behalf of your business, Article 28 of the UK GDPR generally requires an appropriate written contract containing specific provisions.
These include obligations relating to processing instructions, security, sub-processors, assistance with data subject rights and the return or deletion of personal data.
The Information Commissioner's Office guidance on controller and processor contracts explains the relevant requirements.
ICO
For example, if you outsource payroll administration, you should establish how employee information will be processed, secured and handled when the arrangement ends.
The agreement should reflect the actual data processing arrangements rather than relying on a generic confidentiality statement.
7. Dispute resolution and governing law: know what happens when you disagree
A dispute resolution clause explains how contractual disagreements should be handled. A governing law clause identifies which legal system applies to the agreement, while a jurisdiction clause addresses where disputes may be heard.
These provisions can affect the time, cost and complexity of resolving a commercial disagreement.
For small businesses, a proportionate dispute resolution process is particularly important.
Look for a practical process before court action
A contract may require the parties to attempt negotiation or mediation before starting formal proceedings.
For example, it might provide for an initial written complaint, followed by discussions between senior representatives.
If the dispute remains unresolved, the parties may agree to consider mediation.
Such a process can sometimes prevent a relatively small disagreement from escalating into expensive litigation.
However, the wording needs to be clear.
A clause that simply states that parties should "resolve disputes amicably" may provide little practical guidance.
Check the governing law and jurisdiction
If your business is based in England and your supplier operates elsewhere, the agreement may specify that disputes are governed by another country's law.
That can introduce additional complexity.
Even within the UK, England and Wales, Scotland and Northern Ireland have distinct legal systems.
For a small business operating mainly in England and Wales, agreeing to an unfamiliar legal jurisdiction may create unnecessary expense or uncertainty.
Before signing, identify:
Governing Law: Which legal system applies to the contract.
Court Jurisdiction: Which courts may hear a dispute.
Negotiation Requirements: Whether the parties must attempt discussions first.
Mediation Provisions: Whether alternative dispute resolution is required or encouraged.
Formal Notice Requirements: How contractual complaints and legal notices must be delivered.
More complex agreements may contain arbitration provisions, which require separate consideration of the process, costs and enforceability.
Service agreement checklist: 7 clauses at a glance
The following table summarises what you should look for and the potential consequences of unclear wording.
| Contract clause | What you should check | Potential risk |
|---|---|---|
| Scope of services | Deliverables, exclusions, performance standards and additional work | Unexpected charges or incomplete work |
| Payment terms | Price, invoice dates, deposits, VAT and late payment provisions | Cash flow problems and payment disputes |
| Responsibilities and deadlines | Obligations, milestones, dependencies and delays | Missed deadlines and disagreements over responsibility |
| Limitation of liability | Financial caps, exclusions, indemnities and insurance | Unnecessary financial exposure |
| Termination rights | Notice periods, renewal, cancellation fees and handover | Being tied to an unsuitable agreement |
| Intellectual property and confidentiality | Ownership, permitted use, confidentiality and data protection | Loss of control over business assets or information |
| Dispute resolution and governing law | Negotiation, mediation, legal jurisdiction and formal notices | Expensive or complicated disputes |
You do not necessarily need every provision to favour your business.
The objective is to understand the risks, decide whether they are commercially acceptable and avoid agreeing to obligations you have not properly considered.
Five warning signs that a service agreement needs closer attention
Sometimes the most concerning part of a contract is not a particularly complicated clause. It is something the agreement fails to explain.
Before signing, look for these warning signs.
Unclear Pricing: The contract includes additional charges but does not explain how they will be calculated or approved.
Unlimited Supplier Discretion: The other party can materially change services or prices without appropriate safeguards.
One-Sided Termination Rights: The supplier can end the agreement easily while you remain tied to lengthy notice requirements.
Missing Ownership Provisions: The agreement does not establish who owns important work created during the project.
Unbalanced Liability: Your business accepts substantial responsibilities while the supplier's obligations are heavily restricted.
Not every unfavourable provision is automatically unlawful.
Businesses can often negotiate contractual terms and allocate risks between themselves.
However, an agreement should reflect a commercial decision you understand, rather than obligations hidden within standard wording.
Can you negotiate the terms of a service agreement?
Yes. Many service agreement clauses can be negotiated before the contract is signed. You may be able to agree different payment dates, adjust liability limits, clarify deliverables or change termination requirements. The other party does not have to accept your proposals, but asking for reasonable amendments is a normal part of commercial contracting.
The key is to identify which provisions genuinely matter to your business.
If you are commissioning a short project worth £500, extensive negotiations over every clause may not be proportionate.
However, a contract worth £30,000 annually, involving sensitive customer data and a 3-year commitment, deserves greater attention.
Prioritise the clauses that create the greatest risk
Imagine you are signing an agreement with a software supplier.
The monthly fee is affordable, and the supplier has a good reputation.
However, the contract contains 3 provisions you are uncomfortable with:
Automatic Renewal: The contract renews for another 12 months unless notice is provided 90 days before expiry.
Limited Liability: The supplier's liability is capped at a relatively small amount.
Data Access: There is no clear provision covering the return of your business data following termination.
Instead of rejecting the entire agreement, you could ask the supplier to address these issues.
You might propose a shorter renewal notice period, a more appropriate liability cap and a clear data export process.
The supplier may agree, suggest alternatives or explain why certain terms are necessary.
Whatever the outcome, you can make a more informed decision.
Should you use a service agreement template or have a contract reviewed?
A service agreement template can provide a useful starting point, particularly for straightforward transactions with limited financial exposure. However, templates may contain unsuitable terms, omit important protections or fail to reflect how your business operates. Contract review becomes more valuable where the agreement involves significant payments, ongoing commitments, intellectual property, personal data or substantial potential liability.
The important distinction is between having a document that looks complete and having an agreement that actually reflects your business arrangements.
A template designed for freelance design work may not be suitable for a maintenance contract.
Similarly, an agreement intended for business-to-business services may not provide the provisions required where services are supplied to consumers.
Consumer contracts are subject to additional requirements, including protections under the Consumer Rights Act 2015.
You should therefore consider who your customer is, what services you provide and which legal requirements apply.
For routine commercial documents, Raven Legal offers paralegal services for small businesses, including assistance with service agreements, commercial terms, contract drafting and document review.
Where a contract involves complex legal risks, substantial financial exposure or matters requiring regulated legal services, advice from an appropriately authorised solicitor may be necessary.
What should you do before signing a service agreement?
Before you sign, read the complete agreement rather than relying on the commercial summary or quotation.
Check that all schedules, attachments and referenced terms have been provided.
You should also confirm that the final document reflects any amendments agreed during negotiations.
A practical process is to:
Confirm The Parties: Check the correct legal names, business details and contracting entities.
Review The Commercial Terms: Verify the price, scope, duration and payment arrangements.
Identify Significant Risks: Examine liability, termination, indemnity and ownership provisions.
Resolve Unclear Wording: Ask for clarification or amendments before signing.
Check Referenced Documents: Review schedules, service descriptions and incorporated terms.
Confirm Signing Authority: Ensure the person signing has authority to commit the business.
Keep A Complete Copy: Retain the signed agreement and any relevant written amendments.
Be particularly careful where the agreement incorporates another document by reference.
For example, a supplier's standard terms may be available through a website link rather than attached to the contract.
Those terms could contain important provisions affecting liability, price increases or termination.
Make sure you know which version applies and how any future changes will be handled.
❓ Service Agreement Clauses in the UK FAQs
-
A typical business service agreement should address the scope of services, payment terms, responsibilities, deadlines, liability, termination, confidentiality, intellectual property and dispute resolution. Depending on the services involved, additional provisions may be needed for insurance, data protection, subcontracting or regulatory obligations. The appropriate wording depends on the transaction and the risks each party is accepting.
-
A service agreement can be legally binding when the requirements for contract formation are satisfied, including agreement on sufficiently certain terms, consideration and an intention to create legal relations. A signature is not always essential, although some arrangements are subject to specific formalities. Whether particular provisions are enforceable depends on the wording, applicable law and surrounding circumstances.
-
The expressions are often used interchangeably in commercial arrangements. Both generally describe an agreement under which a person or business provides services to another party. However, a contract for services should not be confused with a contract of service, which is traditionally associated with employment. The actual working relationship matters more than the document's title.
-
A business may be able to terminate a service agreement early if the contract permits it, the parties agree or circumstances give rise to a legal right to terminate. The agreement may impose notice requirements, termination charges or other conditions. Ending a contract without an appropriate legal or contractual basis could expose your business to a claim for breach of contract.
-
Not every small business contract requires a solicitor's involvement. Straightforward commercial documents may be suitable for administrative or paralegal drafting support. However, agreements involving substantial liabilities, complicated indemnities, significant intellectual property or specialist regulation may justify advice from an authorised solicitor. The appropriate level of assistance depends on the value, complexity and potential consequences of the agreement.
Protect your business before signing a service agreement
A well-written service agreement should make your commercial relationship easier to manage, not create uncertainty about your responsibilities.
You should know what the supplier is expected to deliver, what you will pay, who carries the relevant risks and how the arrangement can end.
If any of those points remain unclear, it is sensible to resolve them before signing rather than relying on an informal understanding.
At Raven Legal Assistance, we help small businesses, sole traders and individuals across England and Wales prepare and review routine legal documents, including service agreements, commercial terms and business correspondence.
Our fixed-fee approach provides practical documentation support without unnecessary complexity. Raven Legal is a paralegal service rather than a regulated solicitors' firm, and matters requiring reserved legal activities or specialist regulated advice may need to be referred to an authorised professional.
Need help understanding or preparing a business service agreement?
Contact Raven Legal Assistance on 0800 949 9401 or email jw@ravenlegal.co.uk to discuss your contract and the document support available.
Private parking charge rejected: what to do before appealing again
If your private parking appeal has been rejected, you may still be able to challenge the charge through an independent appeals service. The next step depends on which parking company issued the notice and whether it belongs to the British Parking Association (BPA) or International Parking Community (IPC). You will usually need to act within 28 days of the rejection, although you should check the deadline stated in your letter. Before appealing again, review the operator's reasons, gather supporting evidence and check whether the charge was issued correctly.
Receiving a rejection letter can be frustrating, particularly if you believe you paid for parking, followed the displayed rules or were charged because of a genuine mistake.
However, a rejection from the parking company does not automatically mean the charge is legally enforceable. It means the company has decided not to cancel it through its own complaints and appeals process.
Understanding the distinction between a parking company's decision, an independent appeal and a court judgment is important before deciding what to do next.
What happens when a private parking appeal is rejected?
When a private parking operator rejects your initial appeal, you normally have the option to pay the charge or challenge the decision through an independent appeals service.
In England and Wales, private parking disputes are generally civil matters. The parking operator is claiming that you breached the terms of a parking contract, rather than imposing a criminal penalty.
The rejection letter should explain why your appeal was unsuccessful and identify the next stage of the process.
Your options will usually include:
Paying The Charge: You can settle the amount requested if you accept the decision or decide that further action is not worthwhile.
Making An Independent Appeal: You can challenge the decision through POPLA or IAS, depending on the operator's trade association.
Contacting The Landowner: You can ask the business or property owner responsible for the car park to intervene.
Reviewing The Evidence: You can examine whether the operator has demonstrated that the charge was properly issued.
Preparing For Possible Legal Action: If the dispute remains unresolved, you may need to respond to formal debt recovery correspondence or a county court claim.
The important thing is not to confuse an unsuccessful appeal with a court ruling. An operator's rejection is not a judgment against you.
POPLA or IAS: which appeals service should you use?
There are 2 main independent appeals services for private parking charges in England and Wales: POPLA and IAS.
The correct service depends on the parking company's membership of an accredited trade association, not which appeal system you prefer.
| Feature | POPLA | IAS |
|---|---|---|
| Full name | Parking on Private Land Appeals | Independent Appeals Service |
| Parking operators covered | BPA members | IPC members |
| Standard appeal cost | Free | Free |
| Standard appeal deadline | 28 days from rejection | Generally 28 days under the standard procedure |
| Evidence required | Supporting documents and appeal grounds | Supporting documents and appeal grounds |
| If your appeal succeeds | Operator must cancel the charge | Operator must follow the decision |
| If your appeal fails | Operator can continue pursuing payment | Operator can continue pursuing payment |
POPLA's published guidance confirms a 28-day appeal deadline. IAS provides a free standard appeal process, with a separate non-standard procedure that may involve a fee and different conditions. Always follow the current instructions accompanying your rejection.
How to appeal through POPLA
You can appeal through POPLA if your parking charge was issued by a BPA member and your initial appeal has been rejected.
The operator should provide a 10-digit POPLA verification code in its rejection letter.
You will need your parking charge reference, vehicle registration, explanation of the dispute and supporting evidence.
You should submit your appeal within 28 days of the rejection date. POPLA says it is unlikely to accept late appeals unless there are exceptional circumstances.
You can find the application process and guidance on the official POPLA website.
How to appeal through IAS
The Independent Appeals Service considers charges issued by parking operators belonging to the IPC.
Before approaching IAS, you must have challenged the charge with the operator and received its decision.
Your submission should concentrate on why the charge is not justified under the relevant parking terms, applicable law or evidence.
If your main argument is that the parking charge seems unfair, without supporting evidence, you may find it difficult to demonstrate why the operator's decision should be overturned.
An important distinction is that a standard IAS decision is generally binding on the parking operator but not the motorist. Different conditions apply to its non-standard appeals procedure.
Seven things to check before appealing a rejected parking charge
Appealing again should involve more than repeating the explanation you originally submitted.
If the operator has already considered and rejected your argument, you need to identify what evidence was missing, what the company has failed to establish or whether the original decision overlooked something important.
1. Check whether the parking signs were clear
Private parking charges commonly rely on the argument that the driver agreed to contractual terms displayed on signs at the location.
You should consider whether those terms were reasonably visible before or during parking.
Look at the entrance signs and any signs near the parking space.
Questions worth asking include whether the charge was displayed prominently, whether the signs were readable in the lighting conditions and whether restrictions were explained clearly.
For example, imagine you parked at a retail park where the entrance sign advertised free customer parking, but a smaller sign further inside imposed a maximum stay.
If that restriction was not adequately communicated, the signage may be relevant to your appeal.
Photographs taken from a driver's normal approach to the car park can be more useful than close-up photographs showing text that would have been difficult to read from a vehicle.
2. Examine the parking company's photographs
Many private parking operators use automatic number plate recognition (ANPR) cameras to record vehicles entering and leaving a car park.
However, the time between entry and exit is not necessarily the same as the actual period spent parked.
You may have spent time finding a space, reading the signs, using a payment machine or leaving a congested car park.
Suppose you paid for 2 hours of parking but the operator's cameras recorded your vehicle on site for 2 hours and 8 minutes.
That does not automatically prove you parked for 8 minutes beyond your entitlement. The relevant parking period, applicable consideration and grace periods, and the circumstances of your visit need to be examined.
3. Check whether a consideration or grace period applies
Parking rules may allow time to read signs and decide whether to park, along with an appropriate period to leave after parking ends.
These are not necessarily the same thing.
A consideration period relates to the time you need to understand the terms and decide whether to accept them.
A grace period generally relates to leaving the car park after the permitted parking period finishes.
The applicable requirements depend on the rules governing the operator and the circumstances.
Do not assume every car park gives you an automatic 10-minute extension for every situation.
4. Review your payment and parking records
A surprisingly simple error can sometimes be central to a dispute.
You might have paid the correct amount but entered a registration number incorrectly, selected the wrong vehicle in an app or experienced a payment machine fault.
Before appealing, check:
Bank Statements: Look for the payment amount, date and transaction reference.
Parking App Records: Check the session start and end times and the vehicle registration entered.
Payment Receipts: Keep any printed tickets, email confirmations or screenshots.
Machine Fault Evidence: Record error messages or any relevant correspondence with the operator.
Witness Information: Identify anyone who directly observed a payment problem or the relevant circumstances.
A minor registration error should be distinguished from a situation where no payment was made.
Some errors may fall within a parking operator's published cancellation or appeals policy.
5. Check whether the notice was issued correctly
A private parking company must establish a proper basis for pursuing the person it claims is liable.
If the operator is pursuing you as the vehicle's registered keeper rather than identifying you as the driver, the requirements of Schedule 4 of the Protection of Freedoms Act 2012 may be relevant.
For example, where no ticket was placed on the vehicle and the operator wishes to rely on the statutory keeper liability procedure, a postal notice will generally need to be delivered within the relevant 14-day period.
Different requirements apply where a notice was first attached to the vehicle.
There are also requirements concerning the information that must appear in notices.
However, a late or defective notice does not necessarily eliminate a claim against an identified driver. It may instead affect the operator's ability to pursue the keeper under the statutory procedure.
The Protection of Freedoms Act 2012, Schedule 4 explains the conditions for keeper liability in England and Wales.
6. Consider whether disability-related circumstances were overlooked
Parking operators and landowners may have obligations under the Equality Act 2010.
Where a disability affects your ability to access a service, comply with parking arrangements or return to a vehicle within the expected time, reasonable adjustments may be relevant.
For example, if you require additional time to walk between your vehicle and a shopping centre because of a disability, that may be important when challenging an overstay charge.
A Blue Badge is not automatically a complete exemption from private parking conditions. Equally, the absence of a Blue Badge does not mean that disability-related protections cannot apply.
Explain the relevant circumstances clearly and provide suitable supporting information where necessary.
7. Check whether the parking company had authority to issue the charge
A parking operator generally needs an appropriate legal basis to manage parking and enforce charges on the land concerned.
This may arise through ownership, a contract with the landowner or other relevant authority.
If the company cannot establish that it was authorised to enforce the parking terms, this may be relevant to the dispute.
However, simply demanding a copy of a landowner contract does not guarantee that an appeal will succeed.
Your argument should identify a genuine concern about the operator's authority rather than relying on a generic objection.
What evidence makes a private parking appeal stronger?
The strongest appeals usually explain a specific problem and support it with relevant documents.
A detailed account of events is useful, but independent evidence can help demonstrate why the charge should not have been issued.
| Reason for dispute | Evidence worth collecting |
|---|---|
| Unclear parking signs | Photographs showing the entrance, sign positions and visibility |
| Parking payment was made | Bank statement, receipt or parking app confirmation |
| ANPR timing discrepancy | Entry and exit records, payment times and relevant photographs |
| Incorrect vehicle details | Payment confirmation and registration records |
| Disability-related circumstances | Explanation of the relevant needs and appropriate supporting documentation |
| Vehicle was not present | Location records or other evidence showing the alleged event was incorrect |
| Keeper liability disputed | Original notice, envelope, delivery dates and relevant correspondence |
| Parking permission existed | Permit, authorisation email, tenancy document or written permission |
It is also worth keeping a timeline.
Record when you parked, when the charge was issued, when you received it, when you appealed and when the rejection arrived.
This helps you identify inconsistencies and calculate the relevant deadlines.
A practical example of how to present your appeal
Imagine you receive a £100 parking charge after using a supermarket car park.
You originally appealed by explaining that you had been shopping and believed the charge was unfair.
The operator rejects your appeal because its ANPR records show that your vehicle remained on the site beyond the permitted period.
Instead of submitting the same explanation again, you could examine the available evidence more closely.
Perhaps your payment receipt shows when you completed your shopping, photographs demonstrate that the exit was heavily congested, and the operator's entry and exit timestamps do not establish exactly how long your vehicle was parked.
A stronger submission would set out the relevant times, attach the supporting documents and explain why the evidence does not establish a breach of the applicable parking terms.
This is a hypothetical example, not a guarantee that an appeal with similar circumstances will succeed.
What should you do if the operator does not provide a POPLA code?
If a BPA parking operator rejects a qualifying appeal, it should normally provide the information needed to pursue an independent appeal.
Where a POPLA code is missing, contact the operator promptly and request it in writing.
POPLA's guidance explains that a verification code should be provided where the original appeal was submitted within the relevant period.
Keep a record of your request and any response.
Do not assume that requesting the code automatically extends the appeal deadline. If the operator refuses to provide a required code, you can raise the matter with the BPA.
Can you ask the landowner to cancel a rejected parking charge?
Yes. A complaint to the landowner or business responsible for the car park may sometimes lead to a parking charge being cancelled, even after the parking operator has rejected your initial appeal.
For example, you may have received a charge while attending a hospital appointment, visiting a hotel or shopping at a retail centre.
The business may be willing to investigate if you can demonstrate that you were an authorised visitor and explain the circumstances.
Your correspondence should identify the charge, provide proof of your visit and make a reasonable request for intervention.
Keep in mind that the landowner may not have direct control over every enforcement decision.
You should also continue to observe any independent appeal deadline while waiting for a response.
What happens if POPLA or IAS rejects your appeal?
An unsuccessful independent appeal does not, by itself, create a county court judgment or automatically establish that you owe the money through a court order.
However, it does mean the operator can continue seeking payment and may decide to take civil enforcement action.
Your options depend on the evidence, the amount disputed and whether you are prepared to defend a claim.
Can the parking company take you to court?
Yes. A private parking operator may issue a civil claim to recover an unpaid parking charge.
In England and Wales, such disputes are commonly pursued through the County Court, often using the small claims track.
The operator would need to establish a legal basis for the sum claimed.
You would have an opportunity to respond and, where appropriate, defend the claim.
If the operator succeeds, the court may order payment of the charge and recoverable costs.
Importantly, the fact that you lost a POPLA or IAS appeal does not mean a court must reach the same conclusion.
Will a rejected parking charge affect your credit rating?
A rejected parking appeal alone does not create a county court judgment or damage your credit file in the way an unpaid, registered judgment can.
However, the situation becomes more serious if a parking operator obtains a court judgment against you.
In England and Wales, a county court judgment may be registered and affect your credit record. If the judgment is paid in full within 1 month, you can apply for it to be removed from the register. Later payment generally results in the judgment being marked satisfied rather than removed.
This is why you should never ignore genuine court documents.
A demand from a debt collection company is not the same as a court judgment.
Should you ignore debt collection letters?
Ignoring correspondence is generally unwise, particularly once a dispute has reached the formal pre-action stage.
You should distinguish ordinary payment reminders from a formal Letter of Claim and court paperwork.
If you receive a Letter of Claim, review the allegations, supporting evidence and response deadline carefully.
Where the debt is disputed, it may be appropriate to respond in writing, explain the reasons and request relevant documentation.
Raven Legal provides paralegal debt recovery assistance, including support with understanding debt correspondence and preparing clear written responses.
How much can a private parking company charge?
Private parking operators commonly issue charges of up to £100, subject to the applicable rules and circumstances.
However, the amount demanded is not automatically enforceable simply because it appears on a sign.
The charge, contractual terms, relevant parking standards and any additional recovery costs may need to be considered.
The Supreme Court's decision in ParkingEye Ltd v Beavis [2015] UKSC 67 established that a parking charge of £85 was enforceable in the particular circumstances of that case.
It did not establish that every private parking charge, regardless of amount or circumstances, must be paid.
Arguments about unfair charges need to consider the contractual context and legal principles rather than assuming that every charge exceeding the operator's financial loss is invalid.
What about the new private parking rules in 2026?
On 20 October 2026, the UK Government laid a new statutory Private Parking Code of Practice before Parliament.
The code is intended to introduce national minimum standards for private parking operators across England, Scotland and Wales, including requirements covering signs, camera systems, parking periods and appeals.
As at 11 November 2026, the code was still subject to parliamentary scrutiny and had not yet come into force.
The Government indicated that it expected to issue the code on 30 November 2026, subject to the parliamentary process, with commencement 21 calendar days after issue. Transitional arrangements will also be relevant.
Therefore, you should not assume every proposed requirement already applies to an existing charge.
You can check the latest position through the Government's Private Parking Code of Practice.
GOV.UK+1
Common mistakes to avoid when appealing again
Many appeals become harder to resolve because important information is missing or deadlines are overlooked.
Try to avoid the following:
Repeating Your Original Appeal: Address the operator's reasons for rejecting your first challenge.
Missing The Deadline: Check your rejection date and the applicable independent appeal period.
Submitting Incomplete Evidence: Provide relevant documents when making your appeal, rather than assuming they can be supplied later.
Making Unsupported Allegations: Concentrate on what the evidence demonstrates.
Confusing Private And Council Parking Notices: Different procedures and legal frameworks apply.
Ignoring Formal Court Correspondence: Respond appropriately to genuine legal documents and seek regulated legal advice where necessary.
Using Generic Appeal Templates: Explain your own circumstances rather than copying arguments that may not apply.
Remember that POPLA requires you to submit your supporting evidence at the start of the appeal process. Its assessors will not gather missing evidence on your behalf.
A well-organised submission is more useful than an unnecessarily long appeal containing arguments unrelated to the circumstances.
❓ Rejected Private Parking Appeals FAQs
-
Yes, but the second appeal is normally made to an independent appeals service rather than simply asking the original operator to reconsider. If the operator belongs to the BPA, you can generally use POPLA. IPC members use IAS. The process, deadlines and evidence requirements depend on the relevant service.
-
Missing the deadline may mean losing access to the normal independent appeal procedure. POPLA may consider late submissions in exceptional circumstances, while IAS has a separate non-standard process with different conditions. Contact the relevant service promptly, explain the delay and provide any supporting evidence. Do not assume a late appeal will be accepted.
-
An unsuccessful POPLA decision does not itself create a court order requiring payment. However, the operator may continue pursuing the charge and could bring a civil claim. You need to decide whether to pay, attempt a reasonable resolution or remain prepared to defend the claim based on the available evidence and legal position.
-
Yes. A registration error does not automatically mean that an appeal will succeed or fail. The outcome may depend on the nature of the mistake, evidence of payment, the operator's applicable policies and relevant parking standards. Include the correct registration, details entered during payment and proof that you paid for the relevant parking session.
-
Yes. You can question whether the ANPR records accurately establish a breach of the parking terms. The images may show when your vehicle entered and exited the site without proving the precise duration of parking. Payment records, site layout, signage and applicable consideration or grace periods may help explain a discrepancy.
-
Raven Legal provides fixed-fee paralegal support and self-help legal documents for individuals across England and Wales. Assistance may include organising correspondence, preparing written responses and understanding the next steps in a dispute. Raven Legal is not a regulated solicitors' firm, and matters requiring reserved legal activities may need referral to an authorised provider.
Get practical help with your rejected parking charge
If your private parking appeal has been rejected, the most useful next step is to understand exactly why the operator refused to cancel the charge.
Check the deadline, identify the correct appeals service and organise your evidence before submitting another challenge.
You do not need to use complicated legal language. A clear explanation supported by relevant documents is often the most sensible starting point.
At Raven Legal Assistance, we provide practical, fixed-fee document support to individuals across England and Wales, helping you understand unfamiliar correspondence and prepare appropriate written responses.
If you are unsure how to approach your next letter or organise the documents relating to your dispute, explore our paralegal services in the UK.
Contact Raven Legal Assistance on 0800 949 9401 to discuss the paperwork you have received and the practical assistance available.
Can a Private Parking Company Take You to Court?
Yes. A private parking company can take you to the county court to recover an unpaid parking charge, but court action isn't automatic and operators don't always follow through. The charge is a civil debt rather than a fine, so the company has to win a claim before it can enforce anything. Whether it can pursue you depends on who was driving and how closely the company followed the Protection of Freedoms Act 2012.
Advice on this ranges from just ignore it to pay straight away, and neither suits everyone. This guide explains when a claim is possible, who can be pursued, how the process runs, what defences exist and what to do if a claim form arrives. It covers England and Wales. Private parking rules differ in Scotland and Northern Ireland.
⚖️ When Can a Private Parking Company Take You to Court?
They can issue a county court claim once a Parking Charge Notice has gone unpaid and any appeal has failed or been ignored. The claim is civil, based on contract or trespass, so a judge decides whether you owe the money. The company must show the charge was properly brought to your attention on the signs and that it can pursue you personally, as driver or as keeper.
A private parking charge isn't a fine. When you park on private land you enter a contract on the terms shown on the signs, or in some cases the operator relies on trespass. The Parking Charge Notice is the operator's demand under that arrangement, and it isn't a criminal matter.
The leading case is ParkingEye v Beavis, decided by the Supreme Court in 2015. Mr Beavis overstayed a 2 hour free limit at a retail park by nearly an hour and was charged £85. The court held that the charge was enforceable, because the signs were prominent and the operator had a legitimate interest in managing the car park. That doesn't mean every charge will stand. Each claim still turns on its own facts, including the signs, the notices and the amount claimed.
📊 How Likely Is It That a Parking Company Will Actually Sue?
There are no reliable public figures on how many tickets end up in court, so treat anyone quoting a precise percentage with caution. What you can say is that the risk rises as you move through the process. A claim is more realistic once the operator has your address, holds solid evidence and has sent a formal letter of claim that you've ignored.
Some operators decide a small claim isn't worth the cost and stick to reminders and debt recovery letters. That is a commercial choice, not a legal protection, and you can't count on it. The safer approach is to decide early whether you have grounds to challenge the charge, then act on that decision.
🚗 Can the Registered Keeper Be Taken to Court?
Yes, but only if the operator has met the conditions in the Protection of Freedoms Act 2012. It has to be unable to identify the driver, give you a compliant notice to keeper within strict time limits and have obtained your details from DVLA. If it hasn't, it generally has to prove who was driving.
Those conditions sit in Schedule 4 to the Protection of Freedoms Act 2012, which applies in England and Wales only. It covers relevant land, which excludes public highways, parking places run by a traffic authority such as a council, and land where parking is already subject to statutory control.
The timing depends on how the operator first contacted the driver.
| How the operator contacted the driver | When the notice to keeper must be delivered | Earliest it can pursue you as keeper |
|---|---|---|
| Ticket on the windscreen or handed to the driver | In the 28 days that follow the first 28 days after the ticket, so roughly day 29 to day 56 | 28 days after the notice to keeper was given |
| No ticket, for example camera enforcement | Within 14 days beginning the day after the parking ended | 28 days after the notice to keeper was given |
A notice sent by post is presumed delivered on the second working day after posting. The notice must also carry specific information, including the unpaid amount, any discount for prompt payment, how to dispute the charge and a warning about keeper liability. The operator must also have applied to DVLA for your details within the relevant period.
Say a camera operator posts you a notice that reaches you on day 20 after you parked at a retail park. The window for a notice sent without a ticket is 14 days from the end of the parking. That gap could mean the operator can't rely on the Act against you as keeper, although it may still pursue whoever was driving.
2 points catch people out. The most you can owe as keeper is the amount specified in the notice, less any payments, so check whether later demands are higher. And the notice invites you to name the driver, but the Schedule frames that as an invitation rather than a duty. Don't give false information, and get advice before you decide how to respond.
If the car was hired, the hire firm can pass liability to the hirer by giving the operator the required documents within 28 days of the notice to keeper. The operator can then pursue the hirer instead.
Most cases follow the same path, and each stage gives you a chance to resolve the charge before it reaches a judge.
| Stage | What happens | What you can do |
|---|---|---|
| Parking Charge Notice | A ticket on the car or a letter, usually with a discount for prompt payment | Check the signs, the operator and whether you were the driver |
| Appeal to the operator | The operator reviews your reasons | Appeal with evidence such as photos of the signs |
| POPLA or IAS | A free independent appeal after the operator rejects yours | Use the service that matches the operator's trade body |
| Reminders and debt recovery letters | Extra fees may be added | Compare the amount with the original notice and challenge add-ons |
| Letter of claim | Should come with a reply form | Reply using the form within the deadline |
| County court claim | Court papers arrive with a deadline | Respond by the date on the papers |
You must appeal to the operator first. If it rejects your appeal and it belongs to the British Parking Association, you can take the case to POPLA. If it belongs to the International Parking Community, the route is the Independent Appeals Service. Both are free, and both say their decision can't be reviewed later, so put all your evidence in at the start.
There are practical differences. POPLA says the operator must not pursue you while your appeal is with it, and that if the appeal fails and you don't pay within 28 days, the operator may add charges or refer the case to debt collection. The IAS warns that once you appeal to it, you're no longer eligible for a discounted rate if the appeal isn't found in your favour.
The industry code allows an operator to add up to £70 when a charge becomes overdue. The government is consulting on whether to keep, cap or ban that debt recovery fee, which tells you how contested it is. If you're the keeper, remember that the amount you can be asked to pay is limited to the sum stated in the notice to keeper.
Before issuing a claim, the operator or its solicitors should send a letter of claim with a reply form. Under the Pre-Action Protocol for Debt Claims, which applies to businesses claiming a debt from an individual, they shouldn't start court proceedings less than 30 days after the date of the letter, or 30 days after they receive your completed reply form. This is the stage to respond properly, not to ignore.
🛡️ What Defences Do You Have If a Parking Company Takes You to Court?
Common defences include unclear or missing signs, a notice that missed a legal requirement, a claimant with no authority from the landowner, keeper liability that hasn't been established and the claimant being unable to show who was driving. Beavis shows courts will uphold clear terms, so test each point against the facts of your own case.
Signs Were Missing, Unclear Or Hidden
The Notice To Keeper Missed A Requirement Or A Deadline
The Company Cannot Show Authority From The Landowner
The Land Is Not Relevant Land Under The Act
The Claimant Cannot Prove Who Was Driving
The authority point matters because the Act defines a relevant contract as one made with the owner or occupier of the land, or with someone authorised under arrangements made by them. An operator suing in its own name should be able to show that authority.
Signage matters too. For a charge in the nature of damages, the Act requires adequate notice, meaning notices that specify the sum and are adequate to bring the charge to drivers' attention. Photos of the signs on the day, and of where they stood in relation to the bay, are often the best evidence you can have.
Mitigating circumstances such as a breakdown or a medical emergency can persuade an operator or an appeals service. A court tends to focus on the contract, the notices and the evidence, so don't rely on sympathy alone. Arguing only that the charge is too high rarely succeeds, which is the lesson of Beavis.
⚖️ What Happens If You Get a County Court Claim?
Don't ignore it. You must respond by the date on the claim, and you can pay, offer to pay a different amount or defend. If you do nothing, the court can enter a county court judgment against you without hearing your side.
GOV.UK explains how to respond to a court claim for money. You should respond in the same way the claim was made, so respond online if the claim was made online. If you aren't paying the full amount you can ask for another 14 days to respond. Defending a parking claim usually means setting out the points above in your defence and backing them with evidence.
Say a claim form arrives for a £100 charge plus added fees, addressed to you as the keeper, and you never saw a ticket. You would check the notice to keeper dates, the signs and the amount, then defend if the company can't show it met the Act or can't show who was driving. Doing nothing hands the company a judgment without it proving any of that.
A judgment means the court has formally decided that you owe the money. GOV.UK says records of judgments are kept for 6 years unless you pay the full amount within a month, and that this can make it hard to get credit. You can apply to have a judgment cancelled if you don't owe the money or you didn't receive, or didn't respond to, the original claim.
A parking company can't send enforcement agents over an unpaid ticket alone. It needs a court judgment first. If enforcement does start, our guide to what you must not do when bailiffs are at your door explains how to protect yourself.
🔄 What Is Changing With Private Parking Rules?
A statutory Private Parking Code of Practice is still expected but, at the time of writing, has no start date. Meanwhile an industry single code, drawn up by the 2 main trade bodies, has applied since 1 October 2024, with operators given until December 2026 to comply. Some websites quote a £50 cap, but that figure comes from a government code that was withdrawn in 2022.
The Parking (Code of Practice) Act 2019 requires the government to issue a statutory code. The House of Commons Library explains that a first code was published in February 2022 and withdrawn in June 2022 after legal challenges from some parking companies. The government consulted again in 2025 and said it would respond in due course, and no date is known for the code coming into force. When it does, the Act lets the government remove an operator's access to DVLA keeper data if it fails to meet the code, which would make unpaid charges much harder to enforce.
Until then, the rules that matter in court are the Protection of Freedoms Act 2012, contract law and the case law, while POPLA assessors also apply the British Parking Association's code of practice. Check the current position before you rely on any figure, because this area is moving.
❓ Private Parking Court Claim FAQs
-
Yes. Ignoring a ticket doesn't stop a claim, and it removes your chance to resolve the charge cheaply through an appeal. The company still has to prove its case, and a keeper claim must follow the Protection of Freedoms Act 2012. A formal letter of claim is the clearest sign that court action is next.
-
Not by itself. A county court judgment would, and GOV.UK says records of judgments are kept for 6 years unless you pay in full within a month. That is why responding to court papers matters more than the ticket itself.
-
Not for the ticket alone. It needs a court judgment first, and only then can enforcement follow. Anyone who says bailiffs are coming over an unpaid private parking charge, with no judgment, is overstating the position. Ask for the court order details in writing.
-
Usually 6 years from when the claim arose, because contract claims are subject to a 6 year limit under the Limitation Act 1980. Keeper claims also depend on the strict notice timings described above, which can end the company's right to pursue you as keeper much sooner.
-
The notice to keeper invites you to name the driver, but Schedule 4 frames that as an invitation rather than a legal duty. Don't give false information. If you were the driver and the company can prove it, it can pursue you as driver, so get advice before you reply.
-
No. Schedule 4 to the Protection of Freedoms Act 2012 applies in England and Wales only, and private parking rules differ elsewhere. This guide doesn't cover Scotland or Northern Ireland, so check advice that applies where the car was parked.
Need Help With a Parking Charge Notice?
If you've received a Parking Charge Notice, a debt recovery letter or a letter of claim, check the dates and the notices before you reply. Raven Legal provides self-help legal documents and fixed-fee paralegal support in England and Wales, including help with private parking appeals under the Act, POPLA and the IAS. Our tailored letter drafting service can prepare an appeal or reply that fits your situation, and our advice consultation lets you talk through your options. It doesn't include court representation, and if you need a solicitor or barrister we'll say so.
If a debt recovery firm writes about a charge you don't recognise, a prove it letter asks it to show evidence. You can also browse the Letter Factory for other letters.
You can contact Raven Legal or call the freephone number on 0800 949 9401. Raven Legal is a paralegal service for England and Wales, not a regulated law firm or solicitors, and this guide is general information rather than legal advice.
Can Debt Collectors Contact Your Family or Employer? What Are Your Rights?

In England and Wales, debt collectors must not unfairly disclose your debt to your family, friends or employer, and they must take reasonable steps to stop other people finding out you owe money. Those are FCA rules for firms collecting consumer credit debts. A collector can still contact you directly, and your employer can legitimately find out after a court order for wage deductions.
If you've read advice about collectors being allowed to call a relative once, that comes from US law. It doesn't apply here, and the rules in England and Wales work differently. This guide covers what collectors can and can't say, how harassment is defined, what your employer might hear and when, and how to stop unwanted contact.
📞 What Are Your Rights When a Debt Collector Contacts Family or Friends?
Debt collectors must not unfairly disclose or threaten to disclose your debt to a third party, and they must take reasonable steps to stop other people finding out you're being chased. They also can't give details of a debt to someone until they've checked that person is the borrower or acts for the borrower. These are FCA rules for firms collecting consumer credit debts.
The rule uses the word unfairly, so it isn't a blanket ban on any contact with another person. What it does rule out is a collector telling your sister, your neighbour or your colleague that you owe money, or threatening to do so. Collectors must also take reasonable steps to keep your debt private. Post should be properly addressed and marked private and confidential, and a collector's name shouldn't be visible in a way that reveals what the firm does.
A collector also shouldn't send demands to the occupier of an address, or to everyone who shares your name and date of birth or address. The FCA says that kind of approach is likely to breach the rule on disclosing debt details to the wrong person.
Say a collector rings your mum and mentions the balance on your credit card. That is a disclosure you can complain about, and it's a hard one for the firm to defend.
👥 Are Your Family Members Responsible for Your Debts?
Not just because they're related to you. A family member is only responsible for a debt if the law says so, as with council tax shared by people who live together, or if they signed up to it, for example as a joint borrower or guarantor. A debt in your sole name stays yours.
Citizens Advice also explains that you aren't automatically liable for the debts of someone who has died, even if you were their husband, wife or civil partner. Joint debts are different, because each person who is jointly liable is responsible for the whole amount, and a guarantor can be asked to pay if the borrower doesn't.
Say your brother has a loan in his sole name. A collector has no right to ask you to repay it, and no reason to discuss it with you. If you co-signed that loan as a guarantor, the position changes, and you should check the paperwork you signed.
💼 Can Debt Collectors Contact Your Employer?
Not to discuss your debt, because the FCA's rules ban unfair disclosure to third parties. The usual lawful route to your employer is a court order, such as an attachment of earnings order, and that needs a court judgment first. A collector who threatens wage deductions without a judgment is breaking the rules.
The FCA says a firm must not suggest it will start proceedings for an attachment of earnings order when no court judgment has been obtained. It also must not suggest that any action can be taken when legally it can't. So a vague threat to take it from your wages, with no CCJ in place, isn't something the collector can carry out.
If a creditor does have a judgment, it can ask the court to order your employer to take money from your pay. Citizens Advice explains that the court sends you a form to reply to first, so you get a warning. Your employer will know about the order unless it has been suspended, and a creditor can't apply if you owe less than £50.
The FCA's guidance also says it would normally be inappropriate for a collector to visit you at work. Firms must have due regard to reasonable requests about when, where and how they contact you, which includes people who work shifts. Say you work nights and a collector keeps ringing your workplace in the day. A written request to use your mobile outside your shift hours is exactly the kind of request the rules tell firms to respect.
📋 Who Can a Debt Collector Contact and What Can They Say?
This table summarises how the FCA's rules apply to each person a collector might contact. It covers consumer credit debts, so council tax, tax and fines follow different rules.
| Who | What a collector can do | What a collector can't do |
|---|---|---|
| You | Contact you about the debt, explaining who they work for and why they're calling | Contact you at unreasonable times, mislead you about their authority or threaten action that can't legally be taken |
| Family and friends | Make contact only where they don't unfairly reveal your debt and they keep it private | Discuss your balance, name the debt or threaten to tell them |
| Your employer | Act on a court order, such as an attachment of earnings order | Tell them about the debt without a court order or threaten deductions when no judgment exists |
| Neighbours | Send properly addressed post marked private and confidential | Leave letters or messages that reveal the debt or the firm's collection business |
| Your debt adviser or representative | Deal with them on your behalf | Keep up active pursuit while you tell them you're drawing up a repayment plan |
🚨 What Counts as Harassment by a Debt Collector?
Harassment means conduct that alarms you or causes you distress, and a course of conduct under the Protection from Harassment Act 1997 needs at least 2 occasions. For consumer debts, the Digital Markets, Competition and Consumers Act 2024 also bans aggressive practices that use harassment, coercion or undue influence, and FCA rules add limits on timing, tone and disclosure.
The 2024 Act tells decision makers to look at the timing and location of the practice, any threatening or abusive language, whether it exploits a vulnerability and whether it threatens action that can't legally be taken. In practice, these are the things to look for.
Calls Or Texts At Unreasonable Times
Threatening Or Abusive Language
Threats Of Action That Cannot Legally Be Taken
Claiming To Be A Bailiff Or Court Official
Revealing Your Debt To Other People
There are no fixed calling hours in the FCA rules. Firms must not contact you at unreasonable times, so what counts depends on your circumstances. Keep a log of dates, times and what was said, because it turns a vague complaint into evidence.
Section 40 of the Administration of Justice Act 1970 makes it an offence to harass someone over a debt with demands whose frequency, manner or publicity are calculated to alarm, distress or humiliate them or their family or household. It carves out consumer commercial practices covered by the 2024 Act, so for debts owed by consumers the 2024 Act covers that ground instead.
You can also bring a civil claim. Under the 1997 Act, damages can be awarded for anxiety caused by harassment, and a court can grant an injunction to stop it. Get advice before you go down that route.
Say a collector texts you 6 times in a day, then phones your workplace and hints to a colleague that you're in trouble. That combination is the sort of conduct you should log and complain about, because it combines frequency with disclosure to a third party.
🚪Can Debt Collectors Visit You at Home?
They can, but they have to follow rules. Unless it isn't practicable, a collector visiting you must explain the purpose of the visit and give notice of the date and likely time. They can't enter your property without your consent or a court order, and they must leave when you reasonably ask them to. Threatening behaviour is out, and so is visiting at a time when they know or suspect you're particularly vulnerable.
Debt collectors are not bailiffs. Claiming to work on instructions from the courts when that isn't true, or claiming a right of entry when no court order has been granted, is the sort of thing the FCA says firms must not do. If someone turns up at your door and you aren't sure who they are, ask for ID and the name of the firm and creditor. Our guide to what you must not do when bailiffs are at your door covers real enforcement visits in more detail.
✉️ How Do You Stop a Debt Collector Contacting Your Family or Employer?
Write to the collector, name the people you don't want contacted and say how you do want to be contacted, then keep a copy. FCA rules require firms to pay due regard to reasonable requests about when, where and how they contact you. If the contact carries on, complain to the firm and then to the Financial Ombudsman Service.
Write To The Collector And Name The People Not To Contact
Say How And When You Are Happy To Be Contacted
Log Every Call, Text And Letter With Dates
Ask Relatives And Colleagues To Note What Was Said
Complain To The Firm, Then To The Financial Ombudsman Service
Tell the collector if you're getting debt advice or drawing up a repayment plan. A firm must suspend active pursuit of the debt for a reasonable period when you tell it that, and the FCA says that should generally be 30 days where there's a genuine intention to develop a plan. If a debt adviser arranges Breathing Space for you, creditors must stop pursuing qualifying debts for up to 60 days under the Debt Respite Scheme.
Be careful with wording. A letter about contact should ask for the contact to stop, not admit the debt. If the debt is old, disputed or isn't yours, a careless sentence can cause harm. Our tailored letter drafting service can prepare a letter based on your situation, and our debt advice consultation is there if you'd like to talk through your options first.
If you want to settle the debt and keep your family and work out of it, FCA guidance says that refusing to allow alternative, affordable payments after a reasonable proposal is likely to breach the rules. A debt repayment offer letter puts your proposal in writing. Check the age of the debt first, because an offer to pay can count as an acknowledgement of it.
Complain to the firm first and keep its reply. If you aren't happy, you can take the complaint to the Financial Ombudsman Service. Revealing your debt to other people may also be a data protection problem, and you can complain to the ICO about how your personal information has been used. Serious harassment can also be reported to the police.
📝 What If a Collector Contacts You or Your Family About a Debt That Isn't Yours?
Say clearly that it isn't your debt and ask them to stop. FCA rules say a firm must not pursue someone it knows or believes might not be the borrower, and must not ignore a claim that a debt is disputed or keep demanding payment without clear justification or evidence.
A prove it letter asks the collector to show evidence that the debt is yours. If a relative's debt, or a previous occupant's, keeps arriving at your address, our prove it letter for debt collectors is one option, although a short note saying the person doesn't live there may be enough. You don't have to give a collector a forwarding address or contact details for someone else.
Say your adult son moved out 2 years ago and letters keep arriving for him. You aren't responsible for his debts, and a collector shouldn't be sending demands to the occupier or to everyone at the address.
If a collector has already told a relative or colleague about a debt, put that in your complaint with the date and the name of the person who took the call. It is clear evidence of disclosure.
❓ Debt Collector Contact FAQs
-
They shouldn't if you've asked them not to. FCA rules say firms must pay due regard to reasonable requests about when, where and how they contact you, and the FCA's guidance says visiting someone at work would normally be inappropriate. Put your request in writing, keep a copy and note any calls that carry on.
-
No, not unfairly. FCA rules stop firms disclosing or threatening to disclose your debt to a third party, and they must take reasonable steps to stop other people finding out. A collector also can't discuss debt details with someone until they've checked that person is the borrower or acts for the borrower.
-
No. FCA rules say firms must not contact you at unreasonable times, and must respect reasonable requests, for example if you work shifts. The rules don't set fixed calling hours, so the test is what's reasonable for you. Repeated calls or texts can also amount to harassment.
-
They can, but they must explain the purpose of the visit and give notice of the date and likely time unless that isn't practicable. They can't enter without your consent or a court order, and they must leave when you ask. Debt collectors aren't bailiffs, and pretending to be one breaks FCA rules.
-
No. You don't have to tell a collector where you work. If a creditor gets a judgment and applies for an attachment of earnings order, the court will send you a form to reply to, and you need to reply to it. Get advice if you receive one.
Need Help Dealing With a Debt Collector?
If a collector has contacted your family or your employer, or you're not sure what they're allowed to do, get your facts straight before you reply. Raven Legal provides self-help legal documents and fixed-fee paralegal support in England and Wales. Our Letter Factory includes debt letters and templates you can adapt to your situation, and we offer wider debt and early dispute support before things reach court.
You can contact Raven Legal or call the freephone number on 0800 949 9401. Raven Legal is a paralegal service for England and Wales, not a regulated law firm or solicitors, and this guide is general information rather than legal advice. If your matter needs a regulated solicitor, we'll tell you.
How Can You Tell If a Debt Is Statute Barred in England and Wales?

A debt is usually statute barred in England and Wales when more than 6 years have passed since the creditor could first sue, you haven't made a payment or signed a written acknowledgement of the debt in that time, and the creditor hasn't taken you to court. The debt still exists, but the creditor can't win in court if you raise the time limit as your defence.
That sounds simple, but the mistakes tend to happen in the detail. People count from the wrong date, or they send a polite email that restarts the clock without realising. This guide shows you how to check your dates, what resets the time limit, and what to do if a collector or a court claim turns up. It covers England and Wales only.
📌 What Does “Statute Barred” Mean?
Statute barred means the time limit for starting court action over a debt has run out. For most debts in England and Wales that limit is 6 years under the Limitation Act 1980. The debt isn't wiped out. It still exists, and a collector can still ask you to pay it, but they can't win a court case over it if you defend the claim on limitation.
The FCA's guidance on statute barred debts confirms that a statute barred debt in England and Wales still exists. That is why a collector can keep writing to you, and why a letter demanding payment doesn't prove the debt can be enforced. You will also see the terms time barred and out of time used for the same thing.
It isn't the same as a debt being written off. Nobody has to cancel anything for a debt to become statute barred, and you won't get a letter telling you it has happened. You have to work it out from the dates.
✅ How Can You Tell If Your Debt Is Statute Barred?
Run through 4 checks. The debt is likely statute barred if more than 6 years have passed since the creditor could first sue, nobody liable for the debt has made a payment in that time, you haven't signed a written acknowledgement of it, and the creditor hasn't started court action. If any of those fail, treat the debt as still enforceable.
The checks on payments, acknowledgements and court action are usually quick, because you can look through your own records. The date the 6 years starts is where most people go wrong.
📅 When Does the 6 Years Start?
The 6 years runs from the date the creditor first had the right to sue, which lawyers call the cause of action. For a simple unpaid bill, that is generally the date payment fell due and wasn't made. It isn't the date of the last letter, the date the debt was sold, or the date the debt dropped off your credit file.
Credit cards and loans are trickier. In a 2019 case about a credit card, the Court of Appeal held that the 6 years starts when the time given in the creditor's default notice runs out, not from your first missed payment. The case is Doyle v PRA Group (UK) Ltd. The reasoning rests on the default notice rules in section 87 of the Consumer Credit Act 1974, which cover regulated credit agreements generally, so find out the default notice date before you do the sums.
HM Treasury confirmed plans in May 2026 to reform the Consumer Credit Act, including moving many of its information requirements into FCA rules. That needs new legislation and FCA consultation first, so check the current position on default notices before you rely on this point.
Say you made your last credit card payment in March 2019 and the default notice period ended in May 2019. You haven't paid anything or written to the creditor since, and there's no court judgment. The 6 years ran out in May 2025, so by October 2026 the debt is likely statute barred.
🔄 What Restarts the 6 Year Clock?
Any payment towards the debt, however small, restarts the clock. So does a signed written acknowledgement that the debt is yours. Both give the creditor a fresh 6 years to sue, as long as the debt wasn't already statute barred when it happened.
Section 29 of the Limitation Act 1980 says the right to sue is treated as arising again on the date of the payment or acknowledgement. Section 30 adds that an acknowledgement must be in writing and signed by the person making it, although an agent can make it for them. Once a debt is already statute barred, a later payment or acknowledgement doesn't bring it back to life.
Be careful with the word writing. Citizens Advice warns against contacting a creditor in any written form when the time limit may be close, including texts, emails and online chat, and says you can phone to check details. A phone call alone isn't a signed written acknowledgement, but a card payment taken over the phone is still a payment.
Joint debts add a twist. If either of you makes a payment, the clock restarts for both of you. If only 1 of you writes to acknowledge the debt, it restarts for that person only.
| Action | Restarts the clock? | Notes |
|---|---|---|
| Any payment, even £1 | Yes, while the claim is still within time | A small payment can still count. |
| Payment by a joint debtor | Can restart it for all joint debtors | Check whether an ex-partner or co-borrower paid. |
| Signed written acknowledgement | Yes, for the person acknowledging it | Emails and texts can sometimes qualify. |
| Phone call with no payment | Not on its own | An oral acknowledgement is not a signed written acknowledgement. |
| Letters or calls from the creditor | No | Their contact alone does not restart the clock. |
| Debt sold to a new company | No | A sale does not, by itself, restart the clock. |
| Court claim brought within the limitation period | Different effect | Proceedings can preserve the claim. Respond by the court deadline. |
| Checking your credit report | No | Checking alone is not a payment or acknowledgement to the creditor. |
Say you paid £10 towards an old catalogue debt in 2022. The 6 years restarted then, so the debt couldn't be statute barred before 2028, whatever the original default date was. Or say you emailed a collector in 2024 telling them you know you owe the money and will pay when you can. If the debt was still in time, that could count as a signed written acknowledgement and push the date out to 2030 at the earliest.
🔍 How to Check Your Dates Without Restarting the Clock
The aim is to gather facts without admitting anything. These steps usually give you most of what you need.
Check Your Free Credit Reports For The Default Date
Look Through Bank Statements For Your Last Payment
Search Old Letters And Emails For Anything You Signed
Phone The Creditor To Ask For Dates Only
Find Out Whether A Joint Debtor Has Paid Anything
A default date on your credit report is a useful clue, but it isn't the same as the date the 6 years starts, so treat it as a starting point. If you phone the creditor, ask for the date of the last payment and the date any default notice was sent. Don't say the debt is yours, don't promise to pay, and don't make a payment on the call. Keep your own notes of what was said.
If the dates won't line up, don't guess. Free debt charities such as Citizens Advice and National Debtline can help you work it out, and our debt advice consultation is there if you'd rather talk through your paperwork with someone.
⚖️ Which Debts Follow Different Rules?
The 6 year rule covers most unsecured consumer debts, but some situations work differently. Don't assume the headline rule fits yours.
| Situation | What changes |
|---|---|
| Credit cards, loans, overdrafts and catalogue debts | Usually 6 years, with the start date often tied to the default notice for credit covered by the Consumer Credit Act |
| Mortgage shortfall after repossession | 12 years for the main amount owed and 6 years for interest |
| County Court Judgment | The time limit can't be used as a defence once a judgment exists, and a judgment that is 6 years old or more needs the court's permission before bailiff enforcement |
| Breathing Space under the Debt Respite Scheme regulations | If the time limit would run out during Breathing Space or within 8 weeks of it ending, it is extended to the end of that 8 week period |
| Scotland | A 5 year prescriptive period applies, and the debt is extinguished rather than just unenforceable |
A County Court Judgment is the exception people most often get wrong. It isn't treated as statute barred in the same way, because the debt has been turned into a court order. Section 24 of the Limitation Act 1980 sets a 6 year limit on starting an action on a judgment, and under Civil Procedure Rule 83.2 a creditor needs the court's permission to issue a warrant or writ once 6 years or more have passed since the judgment. So an old CCJ is harder to collect, but it hasn't disappeared.
Tax debts, benefit overpayments and some other public body debts follow their own rules, so check the specific time limit before you rely on the 6 years.
📞 What Should You Do If a Debt Collector Contacts You?
If you're sure the debt is statute barred, you can write to the creditor to say so and stop the contact. Citizens Advice suggests including a statement that you don't admit any liability for the claim. Don't say you're unsure what you owe or that the amount is wrong.
Only send that kind of letter if you're confident about the dates. If you aren't, and the debt is still in time, a badly worded letter could hand the creditor a fresh 6 years. This is where wording matters. Our tailored letter drafting service can prepare a reply to a collector that fits your dates, so you aren't relying on a generic template. Send the letter by recorded delivery, or ask the Post Office for free proof of postage, so you can show when it went.
If you don't recognise the debt at all, a prove it letter for debt collectors asks the collector to show evidence that it is yours. It won't answer a question about time limits, so don't rely on it when you know the debt is yours.
Collectors regulated by the FCA have rules to follow. Once you've said you won't pay because the debt is statute barred, they must not keep demanding payment. They also shouldn't suggest you may be taken to court when they know, or ought to know, that the time limit has run out. If a collector keeps chasing after your letter, complain to the firm first, and then to the Financial Ombudsman Service if you're not happy with the reply.
⚖️ What Happens If You Get a Court Claim for a Statute Barred Debt?
Don't ignore it. The court won't assume the debt is out of time, so you need to respond by the date on the claim and tell the court the debt is statute barred as your defence. If you do nothing, the court can enter judgment against you even though the debt was out of time.
GOV.UK explains that you can pay the full amount, offer to pay a different amount or defend the claim, and that you can ask for another 14 days to respond if you aren't paying in full. For a debt you believe is statute barred, defending is the route that matters. A judgment can stay on your credit file for 6 years and make credit harder to get.
Say a claim form arrives for a credit card you last paid in 2018, with no payment or written acknowledgement since. You would still need to file a defence saying the debt is statute barred. If you didn't, a judgment could be entered and the time limit would no longer help you.
A formal letter of claim is different from a routine collection letter. Under the Pre-Action Protocol for Debt Claims, it should come with a reply form, and the creditor shouldn't start court proceedings until 30 days after the date of the letter, or 30 days after they receive your completed reply form. Respond to it rather than ignoring it.
If a judgment has already been made and you think the debt was barred when the creditor applied, you might be able to ask the court to change it, so get advice quickly. If enforcement has already started, our guide to what you must not do when bailiffs are at your door covers the mistakes to avoid.
If a claim lands, speak to a free debt adviser straight away. As a paralegal service for England and Wales, we can help you prepare forms and evidence, but conducting litigation is a reserved activity, so for that we would refer you to a regulated solicitor.
⚠️ What If the Debt Isn't Statute Barred?
Then it's still enforceable, and ignoring it is the riskiest option. The creditor can start a court claim, and a judgment adds to your problems. Most people in this position are better off dealing with the debt on purpose.
Ask For A Full Statement Of The Balance
Work Out What You Can Genuinely Afford
Get Free Debt Advice On Your Options
Think before you send a repayment offer. An offer to pay, or a first payment, restarts the clock while the debt is still in time. That is fine if you plan to repay it, but it isn't something to do casually. If you're ready to make an offer, a debt repayment offer letter puts it clearly in writing.
❓ Statute Barred Debt FAQs
-
Yes, they can still write or phone, because the debt still exists. They can't succeed in court if you raise the time limit. FCA rules say firms must stop demanding payment once you tell them you won't pay because the debt is statute barred, and they mustn't mislead you about court action.
-
It can. The credit file clock and the limitation clock are separate. A default normally drops off 6 years after it was recorded, so a debt can be statute barred and still showing, or gone from your file but not barred, especially if you've kept paying. Check your dates rather than relying on your credit report.
-
Yes, debts can still be sold. A sale doesn't restart the clock, and the new owner takes the debt as it stands. If it was statute barred before the sale, it stays that way, although the new company may still write to you.
-
Not in the same way. Once a judgment exists, you can't use the time limit as a defence to the original debt. After 6 years the creditor needs the court's permission before enforcing by warrant or writ, which makes an old CCJ harder to collect, but it doesn't disappear automatically. Get advice about any judgment that's over 6 years old.
-
Yes. Any payment, even £1, restarts the 6 years while the debt is still in time, and a payment by a joint debtor restarts it for everyone liable. Once the debt is already statute barred, a payment doesn't bring the time limit back. If you're close to the 6 year mark, don't pay anything until you've checked your dates.
-
No. In Scotland the prescriptive period is 5 years, and a debt that prescribes ceases to exist rather than just becoming unenforceable. This guide covers England and Wales only, so get advice that applies to Scotland if that's where you live.
Need Help Checking an Old Debt?
If you've got an old debt letter and you're not sure whether the 6 years has run out, get the dates straight before you reply. Raven Legal provides self-help legal documents and fixed-fee paralegal support in England and Wales. Our Letter Factory includes debt letters and templates you can adapt to your situation, and we offer wider debt and early dispute support before things reach court.
You can contact Raven Legal or call the freephone number on 0800 949 9401. Raven Legal is a paralegal service, not a regulated law firm or solicitors, and this guide is general information rather than legal advice. If your matter needs a regulated solicitor, we'll tell you.
What You Need to Know About the New Tenancy Law Changes in the UK (2025/2026)

The private rental sector in England is about to go through some of its biggest reforms in decades. If you rent out property or are worried about your rights as a tenant, here’s a simple guide to what’s changing, when it’s likely to happen, and what you should do.
🔍 Key Changes in the Renters’ Rights Bill / Reformed Tenancy Laws
Here are some of the big updates:
Abolition of Section 21 “no-fault” evictions
Landlords will no longer be able to evict tenants without giving a reason under Section 21. Instead, they must use Section 8 or other legal grounds.Fixed-term tenancies will become periodic
That means tenancies that currently have, say, a 12-month term will convert to rolling/month-by-month tenancies once the changes take effect.Stricter rules on rent increases
Rent increases will be more controlled — landlords must follow proper notice procedures, and rent hikes will likely be limited in frequency. Arbitrary or frequent hikes will be harder.Ban on excessive upfront charges
Landlords will be restricted in how much they can demand before a tenancy begins. In many cases, just one month’s rent and a deposit will be allowed; large upfront payments beyond that may be outlawed.Better protection and clearer rights for tenants
Tenants will have more security and better standards in their rental homes. This includes tougher obligations on landlords for property conditions, possibly new dispute resolution routes (like ombudsman services) and better clarity on rights when landlords don’t follow rules.
📅 When Will This Happen?
The Bill (called the Renters’ Rights Bill or similar names) is progressing through Parliament.
Expected to receive Royal Assent (official approval) in autumn 2025.
Full implementation of most changes likely in early 2026.
⚠️ What This Means for You
If you’re a tenant, you’ll have more rights: fewer unexpected evictions, clearer rules for rent increases, and less upfront cost burden.
If you’re a landlord, you’ll need to prepare:
• Update tenancy agreements to reflect periodic terms.
• Ensure you have valid grounds allowed under law for evictions.
• Avoid demanding too much upfront rent.
• Keep records of repairs and property condition — stronger legal obligations will come.
✅ How This Connects with Raven Legal Assistance
With all these changes, you might find yourself thinking: “What do I do now?” That’s where tools and templates come in handy.
Ready-made tenancy letters (coming soon!) can help you send notices, communicate with landlords/tenants, or request deposit returns clearly.
If you need a letter tailored to your exact situation, you can use the tailored drafting service.
And if you have questions about your specific tenancy situation, booking an Hourly Advice Consultation gives you legal guidance without full representation.
💬 Final Thoughts
These reforms are meant to make renting fairer and more secure — but change always means people need to adapt. If you’re renting, being prepared helps. If you’re a landlord, now’s the time to review your paperwork, practices, and maybe communication style.
Understanding Divorce and Parenting Agreements in the UK: A Step-by-Step Guide

Going through a divorce or separation can feel overwhelming, but having a clear understanding of the process can make things much easier. Many people are unsure where to start, how to handle parenting arrangements, and what role the court plays in financial matters. This guide sets out the key steps.
1. Starting the Divorce Application
The first step is filing a divorce application with the family court. This can usually be done online. The court fee for a divorce is currently £612. Alongside the application, you will need to provide your marriage certificate and some basic details.
2. Parenting Agreements
For parents, it is important to agree where children will live, how time will be shared, and who will make decisions about schooling, health, and other matters. A written parenting agreement can help reduce conflict and provide stability for children. While not legally binding on its own, it demonstrates cooperation and can be referred to if disagreements arise.
3. Consent Orders
If both parties agree on financial matters — such as property, pensions, or ongoing maintenance — these arrangements can be made legally binding through a consent order. The order is submitted to the court for approval by a judge, usually without a hearing. This ensures clarity and prevents either party from making future claims.
4. Why Preparation Matters
Good preparation at the start makes the process smoother and less stressful. Gathering financial documents, thinking carefully about practical arrangements for children, and recording any agreements can save time and help the court (if involved) understand your situation more clearly.
Final Thoughts
Divorce and separation are challenging, but they don’t have to be confusing. With the right steps in place, you can reach fair and workable arrangements for both finances and children. Taking the time to plan ahead can make the process easier for everyone involved.
Bailiffs at the door: 15 things you must not do (UK)
When an enforcement agent (“bailiff”) visits, what you don’t do matters as much as what you do. Stay calm, keep the door closed, and read this list so you don’t accidentally make things worse.
England & Wales. General information—not legal advice. If you’re unsure, get help fast.
1) Don’t open the door
Most bailiffs can only enter by peaceful entry (an unlocked/open door or being invited in). Talk through the closed door or from an upstairs window. Keep doors and easily-opened windows locked.
2) Don’t let them in “just to talk” (or to use the toilet/phone)
If they cross the threshold once, they may list (“take control of”) goods inside. Keep conversations on the doorstep with the door closed.
3) Don’t sign anything on the doorstep under pressure
A “quick signature” is often a Controlled Goods Agreement (CGA). If you can’t keep the payments, missing one can lead to removal of goods. Read it properly first or ask for it by email.
4) Don’t make payment promises you can’t keep
Agreeing to unaffordable instalments will backfire. Offer realistic, budget-based payments only—after you’ve checked your finances.
5) Don’t ignore ID and paperwork
Ask them to show ID and their certificate number, and to confirm what debt, which court order/warrant, and which creditor. Take notes (time, names, reference numbers). Photograph documents through the glass if needed.
6) Don’t assume they can break in
For most debts (council tax, parking, consumer credit with a CCJ), they can’t force entry on a first visit. Some exceptions exist (e.g., criminal fines, HMRC) and usually require specific authority. If they claim this power, ask for it in writing.
7) Don’t leave doors or windows open
They can enter through any unlocked entry point. Keep everything shut and locked until they leave.
8) Don’t hand over car keys (and don’t park on your drive)
Vehicles are common targets. If a visit is likely, park your car away from your home (not on your drive or directly outside).
Do not move or interfere with a vehicle that’s already clamped or listed on a CGA.
9) Don’t let them take essential household items
Bailiffs can’t take basic domestic necessities (e.g., fridge, cooker, beds, kids’ items). They also shouldn’t take tools of the trade you reasonably need for work (up to a statutory limit), or Blue Badge/ Motability vehicles. Challenge politely if they try.
10) Don’t lie, but don’t overshare
Keep it factual: confirm your name and address; don’t volunteer extra personal information or admit liability on the doorstep.
11) Don’t get physical or aggressive
Obstruction can create separate problems. Stay calm, keep the door closed, and record details.
12) Don’t deal by phone if you’re flustered
Ask for everything in writing (email is fine). Written trails protect you and reduce pressure tactics.
13) Don’t ignore the earlier letters
A bailiff visit usually follows a Notice of Enforcement. If you missed it, ask the company to email copies of all notices and the balance breakdown.
14) Don’t assume you have no options if you’re vulnerable
If you’re ill, disabled, recently bereaved, pregnant, a single parent with young children, or have mental-health issues, tell them (in writing) and ask for a hold while you get debt advice. Ask for their vulnerability policy.
15) Don’t wait—act the same day
Email the bailiff firm to request:
a hold on enforcement while you seek advice,
a full breakdown of fees and balance, and
all copies of notices/warrants.
Then speak to a debt adviser or legal support.
What to do instead (quick checklist)
Keep the door closed; speak politely through it.
Ask for ID, reference numbers, and documents.
Take notes/photos.
If you can pay something, make a realistic offer in writing.
If you’re vulnerable, say so in writing and ask for a hold.
Move your car away from home (unless clamped/CGA).
Get help quickly.
Need a letter?
If your case hasn’t reached enforcement (no court order yet), start with a simple “prove-it” letter to make collectors show evidence before you engage. If you’re already at bailiff stage, we can draft a short hold & vulnerability request email for you the same day. Call 0800 949 9401 or email jw@ravenlegal.co.uk.
Raven Legal Assistance provides self-help legal documents and fixed-fee paralegal support for England & Wales. We’re not a regulated law firm. If your case is urgent or complex, we can introduce a solicitor/barrister.